Insurance
Insurance
Profitable, ready-to-quote insurance leads to help grow your book of business
Profitable, ready-to-quote insurance leads to help grow your book of business
Profitable, ready-to-quote insurance leads to help grow your book of business
Buy from a platform built directly from the feedback of 100+ insurance agents, so you get the right leads at the right price: source, consent, and cost visible before you buy. Sign up in 2 minutes, go live, and get leads delivered straight to your CRM while your consumers are still shopping.
Buy from a platform built directly from the feedback of 100+ insurance agents, so you get the right leads at the right price: source, consent, and cost visible before you buy. Sign up in 2 minutes, go live, and get leads delivered straight to your CRM while your consumers are still shopping.
No contracts or paperwork needed. $500 minimum balance to buy your first leads.
No contracts or paperwork needed. $500 minimum balance to buy your first leads.
No contracts or paperwork needed. $500 minimum balance to buy your first leads.


$0
Setup fee
$0
Setup fee
$0
Setup fee
48
states covered
48
states covered
48
states covered
2 min
to go live
2 min
to go live
2 min
to go live
100%
TCPA compliance captured on every lead
100%
TCPA compliance captured on every lead
100%
TCPA compliance captured on every lead
What are insurance leads?
What are insurance leads?
What are insurance leads?
An insurance lead is a person who filled out a quote request, usually on a comparison site, a search ad landing page, or a social campaign, and consented to be contacted about insurance.
Two things separate a lead worth paying for from a wasted one: intent and consent. Every failure mode in this industry, from angry prospects to compliance risk, traces back to a missing one of these two.
An insurance lead is a person who filled out a quote request, usually on a comparison site, a search ad landing page, or a social campaign, and consented to be contacted about insurance.
Two things separate a lead worth paying for from a wasted one: intent and consent. Every failure mode in this industry, from angry prospects to compliance risk, traces back to a missing one of these two.


What insurance leads can you buy on PX Local?
What insurance leads can you buy on PX Local?
What insurance leads can you buy on PX Local?
Life Insurance Agents
Connect with consumers actively exploring life coverage. See key details around coverage needs, household, and intent before you buy.
Join the waitlist
Life Insurance Agents
Connect with consumers actively exploring life coverage. See key details around coverage needs, household, and intent before you buy.
Join the waitlist
Life Insurance Agents
Connect with consumers actively exploring life coverage. See key details around coverage needs, household, and intent before you buy.
Coming Soon
Join the waitlist
Health Insurance Agents
Reach consumers looking for health coverage now. Understand eligibility, household needs, and enrollment timing before you buy.
Join the waitlist
Health Insurance Agents
Reach consumers looking for health coverage now. Understand eligibility, household needs, and enrollment timing before you buy.
Join the waitlist
Health Insurance Agents
Reach consumers looking for health coverage now. Understand eligibility, household needs, and enrollment timing before you buy.
Coming Soon
Join the waitlist
Others
Home, Medicare, Final Expense, and more are on the way. Tell us what you sell, and we'll let you know the day your lines opens.
Join the waitlist
Others
Home, Medicare, Final Expense, and more are on the way. Tell us what you sell, and we'll let you know the day your lines opens.
Join the waitlist
Others
Home, Medicare, Final Expense, and more are on the way. Tell us what you sell, and we'll let you know the day your lines opens.
Coming Soon
Join the waitlist
Buying
insurance leads:
best practices
Buying insurance leads: best practices
Buying insurance leads: best practices
Call ASAP
A lead reaches you moments after the person submits a request. 78% of consumers buy from the company that responds first [Lead Connect], and calling within 5 minutes rather than 30 makes you 21 times more likely to qualify the lead [MIT/InsideSales Lead Response Management study].
Call ASAP
A lead reaches you moments after the person submits a request. 78% of consumers buy from the company that responds first [Lead Connect], and calling within 5 minutes rather than 30 makes you 21 times more likely to qualify the lead [MIT/InsideSales Lead Response Management study].
Match the format to your team: web leads, calls, or appointments.
Web leads arrive as a data record, and you can call, text, or email them. Live calls connect you with a consumer in real time and are priced accordingly. Appointments are scheduled conversations, the most expensive and least common format. Small teams that sell in bursts usually do best starting with web leads on a controlled daily budget; operations with dedicated phone coverage get more from calls.
Match the format to your team: web leads, calls, or appointments.
Web leads arrive as a data record, and you can call, text, or email them. Live calls connect you with a consumer in real time and are priced accordingly. Appointments are scheduled conversations, the most expensive and least common format. Small teams that sell in bursts usually do best starting with web leads on a controlled daily budget; operations with dedicated phone coverage get more from calls.
Follow up, follow up, follow up!
Among insurance leads that convert, 93% respond by the sixth call attempt, yet the average insurance company makes only 1.45 calls per lead [Velocify]. Plan about six calls and five emails over the days following a lead's arrival. Most lost leads result from a cadence that never occurred, not from poor leads.
Follow up, follow up, follow up!
Among insurance leads that convert, 93% respond by the sixth call attempt, yet the average insurance company makes only 1.45 calls per lead [Velocify]. Plan about six calls and five emails over the days following a lead's arrival. Most lost leads result from a cadence that never occurred, not from poor leads.
Choose shared or exclusive deliberately:
A shared lead is sold to multiple agents, commonly three to eight, who all call the same person. An exclusive lead is sold to one buyer. Shared costs less per lead; exclusive converts better per lead. Industry data puts contact rates on exclusive leads at two to three times shared, and close rates at three to five times [source: InsureLeads, 2026]. Shared leads reward speed and disciplined follow-up at lower cost. Exclusive leads reward agents who invest real time in each conversation.
Choose shared or exclusive deliberately:
A shared lead is sold to multiple agents, commonly three to eight, who all call the same person. An exclusive lead is sold to one buyer. Shared costs less per lead; exclusive converts better per lead. Industry data puts contact rates on exclusive leads at two to three times shared, and close rates at three to five times [source: InsureLeads, 2026]. Shared leads reward speed and disciplined follow-up at lower cost. Exclusive leads reward agents who invest real time in each conversation.
How much do insurance leads cost?
How much do insurance leads cost?
Insurance type
Insurance type
CPL Range
CPL Range
Auto
Auto
$5 to $15+
$5 to $15+
Life
Life
$20 to $45
$20 to $45
Home
Home
$10 to $20
$10 to $20
Health
Medicare /
final expense
$20 to $40
$20 to $40
" transform="translate(4 4)" width="15.999999781839222px"/></svg>)
However, price is just the starting point, making cost per lead the wrong metric to optimize for. It's the cost per acquired customer (CPA) that will decide if the leads are worth it.
" transform="translate(5 4)" width="14.222222222222172px"/></svg>)
For example, 100 leads at $5 each with a 2% close rate cost $250 per customer, while 100 leads at $10 each with a 10% close rate cost $100 per customer. The cheapest leads might be the most expensive thing you can buy.
100 × $5 · 2% close rate
per customer
100 × $10 · 10% close rate
per customer

What usually goes wrong when you buy leads
What usually goes wrong when you buy leads
What usually goes wrong when you buy leads
Every insurance agent has a lead vendor story; these are the four we hear most.

01
Oversold leads
The same household sold to five or more agencies, sometimes across networks. By the time you dial, they've been quoted twice and stopped answering. Reselling multiplies the vendor's revenue per lead, and you can't see how many times a lead has been sold before you buy.
02
No real quote request
Disconnected numbers, dead lines, or someone who clicked a sweepstakes ad and never asked for coverage. No request and no consent record means no quote, no bind, and TCPA (the federal law that governs outbound calls) exposure on every dial.

03
Credits that never clear
The lead was bad, the dispute sat for weeks, and the rep went quiet. Every credited lead is refunded revenue, so slow-walking disputes protects their margin while your acquisition cost climbs.

04
The volume treadmill
When quality slips, the standard advice is to buy more and dial harder until a 5% close ratio looks normal. Your cost-per-bound policy climbs in either direction, and the vendor's revenue does too.
01
Oversold leads
The same household sold to five or more agencies, sometimes across networks. By the time you dial, they've been quoted twice and stopped answering. Reselling multiplies the vendor's revenue per lead, and you can't see how many times a lead has been sold before you buy.
02
No real quote request
Disconnected numbers, dead lines, or someone who clicked a sweepstakes ad and never asked for coverage. No request and no consent record means no quote, no bind, and TCPA (the federal law that governs outbound calls) exposure on every dial.
03
Credits that never clear
The lead was bad, the dispute sat for weeks, and the rep went quiet. Every credited lead is refunded revenue, so slow-walking disputes protects their margin while your acquisition cost climbs.
04
The volume treadmill
When quality slips, the standard advice is to buy more and dial harder until a 5% close ratio looks normal. Your cost-per-bound policy climbs in either direction, and the vendor's revenue does too.
01
Oversold leads
The same household sold to five or more agencies, sometimes across networks. By the time you dial, they've been quoted twice and stopped answering. Reselling multiplies the vendor's revenue per lead, and you can't see how many times a lead has been sold before you buy.
01
Oversold leads
The same household sold to five or more agencies, sometimes across networks. By the time you dial, they've been quoted twice and stopped answering. Reselling multiplies the vendor's revenue per lead, and you can't see how many times a lead has been sold before you buy.
02
No real quote request
Disconnected numbers, dead lines, or someone who clicked a sweepstakes ad and never asked for coverage. No request and no consent record means no quote, no bind, and TCPA (the federal law that governs outbound calls) exposure on every dial.
02
No real quote request
Disconnected numbers, dead lines, or someone who clicked a sweepstakes ad and never asked for coverage. No request and no consent record means no quote, no bind, and TCPA (the federal law that governs outbound calls) exposure on every dial.
03
Credits that never clear
The lead was bad, the dispute sat for weeks, and the rep went quiet. Every credited lead is refunded revenue, so slow-walking disputes protects their margin while your acquisition cost climbs.
03
Credits that never clear
The lead was bad, the dispute sat for weeks, and the rep went quiet. Every credited lead is refunded revenue, so slow-walking disputes protects their margin while your acquisition cost climbs.

04
The volume treadmill
When quality slips, the standard advice is to buy more and dial harder until a 5% close ratio looks normal. Your cost-per-bound policy climbs in either direction, and the vendor's revenue does too.
04
The volume treadmill
When quality slips, the standard advice is to buy more and dial harder until a 5% close ratio looks normal. Your cost-per-bound policy climbs in either direction, and the vendor's revenue does too.
What a lead shows you on PX Local
What a lead shows you on PX Local
What a lead shows you on PX Local


The insurance picture
current carrier, policy renewal date, and line details (vehicles and drivers for auto; property details for home).
The consumer
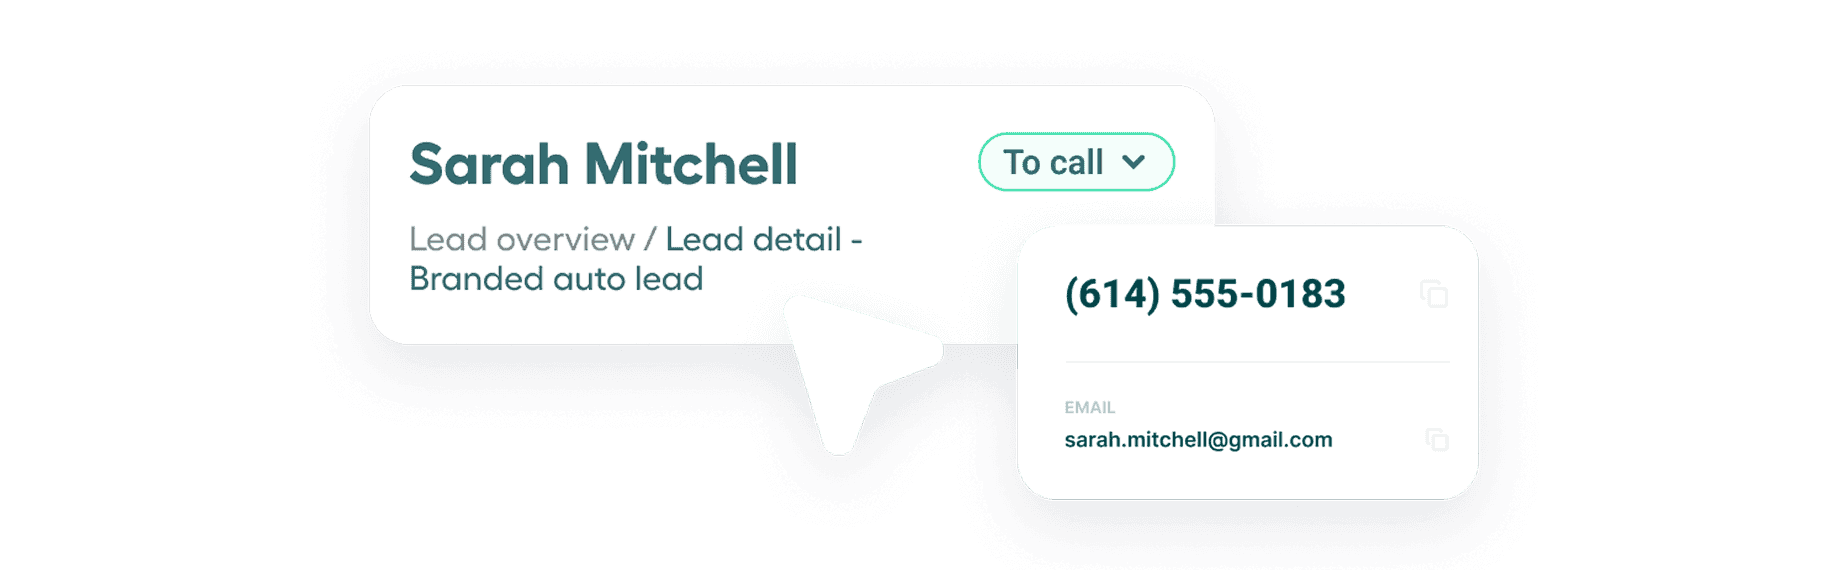
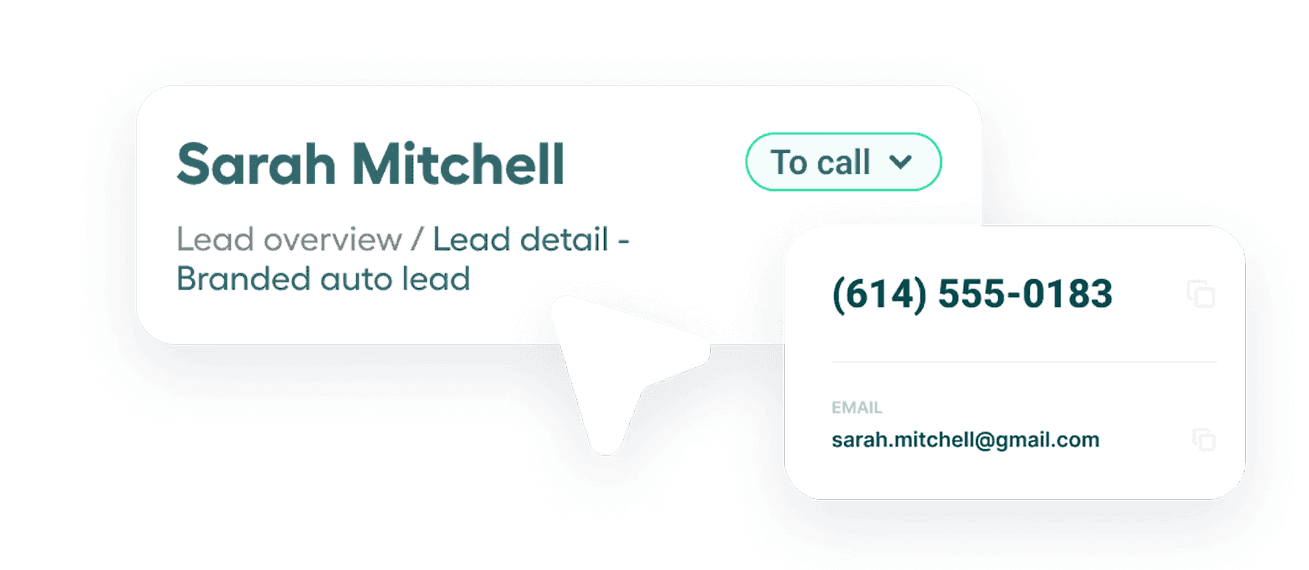
name, contact information, and what they asked to be quoted.


The freshness
lead age in minutes, with hot leads flagged.


The source
where the request was made, with the consent timestamp and an independent (Jornaya) record proving it.
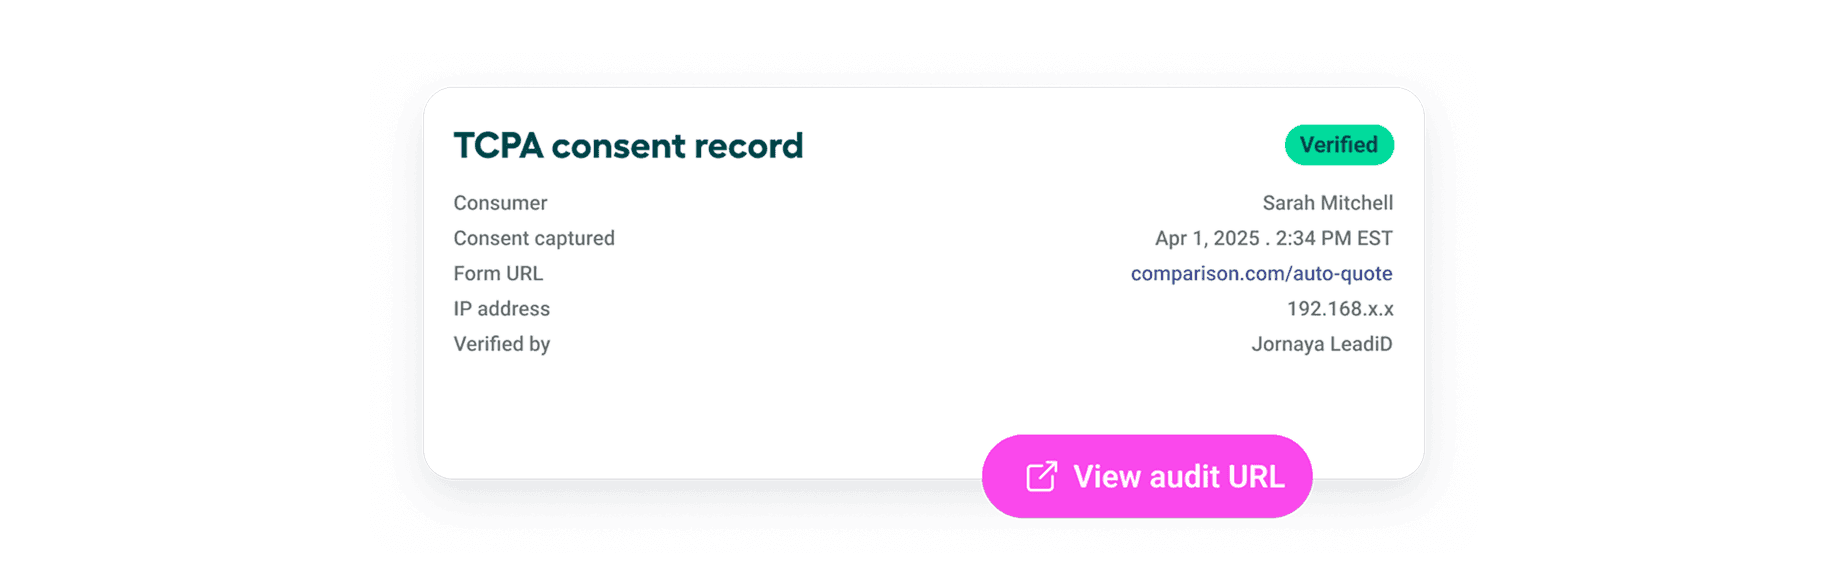

TCPA consent status
captured per lead.


The price
before you commit.
FAQ
Got questions?
Got questions?
What are insurance leads?
Insurance leads are consumers who recently requested insurance quotes and agreed to be contacted by an agent. A lead record includes contact details, the coverage requested, and context like vehicle or property information.
How much do insurance leads cost?
Are insurance leads worth it?
What's the difference between shared and exclusive insurance leads?
Where do insurance leads come from?
How fast should you call an insurance lead?
Can you return a bad insurance lead?
What's a good close rate on purchased leads?
Convert more leads.
Your next customer
is already searching.
Convert more leads.
Set up your account in minutes and decide, one lead at a time, whether we earn your budget.
Set up your account in minutes and decide, one lead at a time, whether we earn your budget.
Powered by
PX Local is a customer acquisition platform for local businesses to grow their book of business profitably, at scale
PX Inc
44 Wall Street, Suite 605,
NY, NY 10005
Questions? Drop an email to:
Powered by
PX Local is a customer acquisition platform for local businesses to grow their book of business profitably, at scale
PX Inc
44 Wall Street, Suite 605,
NY, NY 10005
Questions? Drop an email to:
Powered by
PX Local is a customer acquisition platform for local businesses to grow their book of business profitably, at scale
PX Inc
44 Wall Street, Suite 605,
NY, NY 10005
Questions? Drop an email to: